


Offset accounts explained
If you’re considering buying a home, you may have come across the term “offset account”, as well as a heap of similar words and phrases. It’s important to know what these mean – especially if you want to save yourself time and money. Understanding how an offset account works is particularly useful as having one could save you thousands of dollars in interest and help you pay off your home loan sooner.
What is an offset account?
In simple terms, an offset account allows you to use the balance of a linked transaction account to “offset” (or reduce) the balance of your home loan that interest is charged on.
How does an offset account work?
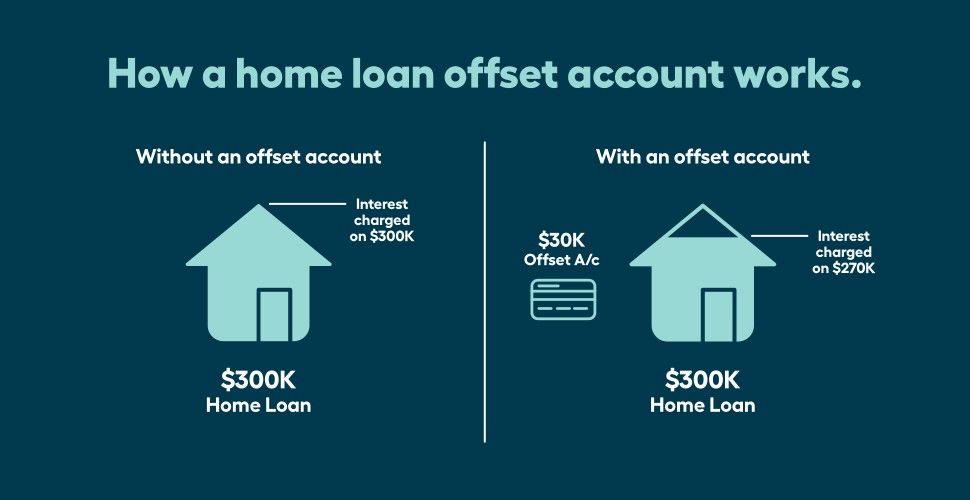
Let’s say you have a home loan balance of $300,000 and $30,000 in your offset account. In this scenario, you would only pay interest on $270,000 (i.e. your home loan balance minus the amount in your offset account). This can save you money on interest over the long term and help you pay off your loan sooner.
When should you offset your home loan?
If you have savings that you may want to put towards a renovation, school fees or something else in the future, those funds can work harder for you offsetting your home loan as opposed to sitting in a savings account.
Plus, your home loan interest rate is often higher than that of a savings account. And, unlike interest earned in a savings account, the interest savings you make by offsetting your home loan are tax free.
Benefits of an offset account
There are a few advantages that come with an offset account.
- An offset account saves you money
Using the money in your offset account to offset the balance of your home loan means you’ll pay less in interest.
- Own your home sooner
Paying less interest on your home loan means you’re chipping away at more of the principal with every repayment. This allows you to pay off your home loan faster and own your home sooner. Win, win!
A couple of clever ways to use an offset account to pay off your home loan sooner
1. Deposit your salary into your offset account
By depositing your salary straight into your offset account, your salary is working harder for you, as interest savings are calculated daily.
Using a credit card throughout the month for all your expenses helps you keep more money in your offset account each day, thereby saving you more on home loan interest. However, it’s important to be disciplined and pay off your credit card in full each month to avoid credit card interest charges.
2. Put any savings straight into your offset account
While you may think a savings account will earn you more interest, your home loan is likely to have a higher interest rate. This means you could save more interest on your home loan than you would earn in a savings account. So put any bonuses, cash gifts, and even your tax refund into your offset account as soon as you can.
How much do you need for an offset to be of benefit?
Having a lazy $100,000 lying around to offset your home loan would be nice (really nice), but that’s going to be unrealistic for most homebuyers. So, what is a good amount to offset your home loan? How much do you need to have to make it worthwhile?
A recent article by financial comparison website Mozo suggests borrowers generally need to maintain around $30,000–$50,000 in an offset before the savings clearly outweigh a typical rate premium or fees, although the exact amount depends on the loan size and pricing.
What’s the difference between an offset account and a redraw facility?
As these two are sometimes confused, it’s worth being super clear about the difference between them. As discussed above, an offset account is an everyday transaction account that's linked to your eligible home loan. The money you keep in the account reduces the amount of your home loan that's used to calculate interest.
A redraw facility, on the other hand, allows you to access (‘redraw’) any funds you’ve made over and above the minimum required by your home loan contract.
100% or partial offset
Offset accounts can be 100% or partial offset. Make sure you check that the full value of your linked account is offset against your home loan, not just a portion of it. Look for home loans that feature 100% offset and you'll know that every dollar in your offset account is working hard to save you money.
Can I have more than one offset account?
While some banks only allow you to have one linked offset account, Great Southern Bank lets you have up to six linked Everyday Accounts*. And what’s more, you can offset 100% of their combined balances against your Offset Variable Home Loan.
If I have a Great Southern Bank home loan with a linked offset account (or accounts), how can I view the details?
You can view any offset accounts linked to your Great Southern Bank home loan in online banking. Simply select your home loan and navigate to the ‘Account details’ section. Similarly, selecting an Everyday Account you’re using as an offset and navigating to ‘Account details’ will show details of the home loan it’s linked to.
*You must maintain a minimum balance of $500 in each offset account to obtain an offset benefit. You will not receive any interest on the funds in your offset accounts.
Great Southern Bank, a business name of Credit Union Australia Ltd ABN 44 087 650 959, AFSL 238317. Conditions, fees and charges apply. This is general information and does not take into account your objectives, financial situation or needs. Consider the appropriateness of the information, including the Terms and Conditions (T&Cs) booklet, before acting on it. The Financial Claims Scheme may apply to this product; refer to the T&Cs for more information.
Contact:
Phone:
Email: